Is Your Coverage Keeping Up with Your Life? 5 Milestones That Require a Policy Check-In

Life moves fast. Between managing a career, maintaining a household, and raising a family, insurance is often something you “set and forget.” However, an outdated policy is often just as risky as having no policy at all.

As your local independent agent, I see firsthand how quickly a “standard” policy can become obsolete. To keep your assets protected and your documentation accurate, here are five major life changes we should review together every year.

Saying “I Do” (Marriage)

Merging two households involves more than just sharing a closet. From an insurance perspective, marriage often unlocks significant multi-policy discounts.

  • Combined Auto: Moving onto a single policy usually lowers your total premium.
  • Liability Limits: With two incomes and combined assets, your underlying liability needs may increase.
  • The “Paperwork” Factor: Updating beneficiaries and legal names is vital for seamless claims processing later.

New Vehicles in the Driveway

Whether you finally bought that electric SUV or handed down the old sedan to a family member, your auto policy needs an immediate update.

  • Replacement Cost: If you bought a new car, you want to confirm you have the right valuation coverage, so you aren’t stuck with a massive gap if the car is totaled.
  • Safety Features: Modern driver-assistance technology can sometimes influence your rates—make sure your agent knows exactly what tech is on board.

Home Renovations and Upgrades

Did you finish the basement during the off-season? Or perhaps you finally upgraded to a professional-grade kitchen?

  • The Replacement Cost Gap: If the cost to rebuild your home increases by $50,000 due to renovations, but your policy limit stays the same, you are underinsured.
  • Material Quality: Upgrading from laminate to quartz or adding a deck changes the footprint and value of your property. We need to document these improvements to reflect the current market value.

Adding a Teen Driver

Adding a teenager to your policy is a major milestone (and a stressful one!).

  • Student Discounts: Many carriers offer lower rates for “Good Students” who maintain a certain GPA.
  • Liability Buffers: Teens are statistically higher risk. This is the ideal time to discuss an Umbrella Policy to protect your savings and home in the event of a significant accident.

Acquiring New Valuables

Standard homeowners policies have “sub-limits” on high-value items like jewelry, fine art, and high-end electronics.

  • The $2,500 Rule: Often, a standard policy only covers jewelry up to a specific (and often low) amount.
  • Scheduled Personal Property: If you received an engagement ring, a luxury watch, or expensive sports equipment this year, we should “schedule” those items individually to provide full replacement value.

Why an Annual Review Matters

Documentation is the foundation of every successful insurance claim. By sitting down once a year, we can adjust your deductibles, hunt for new discounts, and confirm that your coverage limits match your current reality.

An independent agent works for you, not the insurance company. We have the flexibility to shop around and find the right fit as your life evolves.
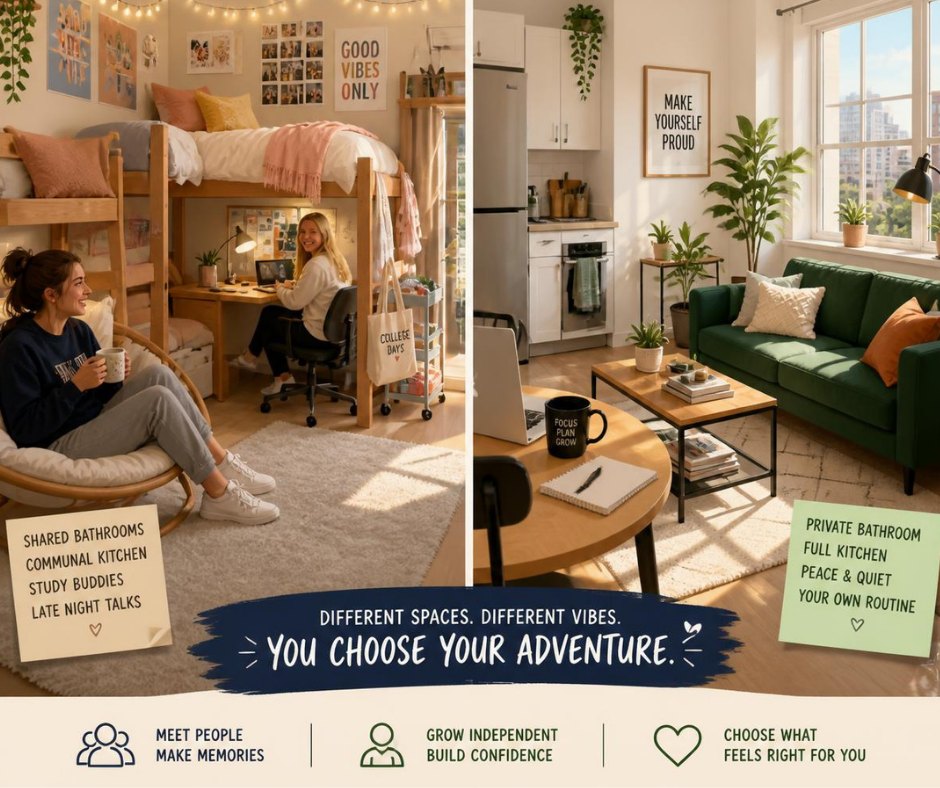
Dorm Rooms vs. First Apartments: The College Bound Insurance Checklist

August marks the official peak of college move-in season. Across the country, students are packing up vehicles with expensive laptops, tablets, bicycles, and specialized gear to head to campus.

While organizing a packing list takes priority, confirming how those physical belongings are protected against theft or damage is a critical step that belongs on a family’s radar before drop-off day. The type of housing a student selects directly dictates how insurance coverage handles their property.

On-Campus Dorms: The Homeowners Insurance Extension

For students moving into an official university residence hall, a separate policy might not be necessary right away. Most standard homeowners insurance policies automatically extend protection to family members who live temporarily on campus.

  • The Sub-Limit Rule: Homeowners policies typically cap off-premises coverage for a student’s belongings at a small percentage of the total personal property limit. If a parent’s policy includes a standard coverage limit, the student’s dorm gear receives a fraction of that total protection.
  • The Deductible Factor: If an expensive laptop gets stolen from a dorm room, a standard home insurance deductible applies first. This out-of-pocket cost can make filing a smaller dorm claim financially impractical.
  • Status Constraints: To qualify for this extension, the student usually must maintain full-time enrollment status and fall below a specific age limit dictated by the carrier.

Off-Campus Apartments: The Standalone Requirement

The moment a student moves into an off-campus apartment, a rental house, or a Greek house under a distinct lease agreement, the umbrella of a parent’s homeowners insurance typically vanishes.

  • Separate Residency: Insurance carriers view an off-campus apartment as a primary, separate residence. Because the student signed a legal lease, they are considered to be living independently, meaning parental policy protections no longer apply.
  • The Landlord Myth: A common misconception is that the property owner’s policy covers a tenant’s belongings. In reality, a landlord’s commercial coverage applies strictly to the physical building structure, not the clothing, furniture, or tech inside individual units.
  • Mandatory Leases: Most modern apartment complexes and private landlords now explicitly require tenants to provide proof of an active renters insurance policy before handing over the keys.

The Value of a Dedicated Renters Policy

A standalone renters insurance policy is highly affordable, usually costing a minimal monthly fee. For off-campus students, this specialized coverage provides two essential pillars of protection:

  1. Personal Property: This pays to repair or replace items like smartphones, textbooks, and electronics if they are stolen or damaged in a covered incident, such as an apartment fire or break-in.
  2. Personal Liability: If a guest slips inside the apartment, or if a student accidentally causes water damage that leaks into a downstairs neighbor’s unit, liability coverage handles the associated legal defense fees and medical bills.

The Bottom Line: Inventory the high-value items heading to campus this month. Taking ten minutes to call an independent agent helps verify whether an existing home policy offers enough dorm coverage, or if a quick, inexpensive renters policy needs to be put in place to shield a student’s assets before move-in day.

Key words – East Douglas Insurance, Douglas, Douglas Massachusetts, renters insurance, Dorm room insurance, College student insurance, Homeowners insurance for college students

The 10-Minute Insurance Checkup: Why Your Policy Needs a Financial Tune-Up Today

Most of us treat our insurance policies like a gym membership: we pay the monthly fee, feel good that we have it, and then promptly forget about it. However, insurance isn’t just a “set it and forget it” expense. It is a living part of your financial portfolio.

Think of an insurance review like a financial checkup. Just as a quick visit to the doctor can catch small issues before they become major health problems, a 10-minute policy review can prevent “coverage gaps” that lead to massive out-of-pocket expenses later.

The best part? It doesn’t take an entire afternoon. In just 10 minutes, you can ensure your protection is as strong as it needs to be.

Your 10-Minute Insurance Checklist

Here are five high-impact updates you can make today to keep your policy performing its best:

1. Update Your Home Inventory

Did you buy a new laptop, upgrade your kitchen appliances, or receive new jewelry? If your home inventory list is two years old, you are likely under-insured. Taking a few photos or a quick video walkthrough of your home ensures that if the worst happens, you’re reimbursed for what you actually own today.

2. Add or Remove Vehicles

Life moves fast. Maybe you sold an old car that’s still sitting on your policy, or perhaps you have a teen driver who needs to be officially added. Adjusting your fleet ensures you aren’t paying for “ghost” coverage or, conversely, driving without protection.

3. Ensure Coverage Keeps Up with Inflation

This is the most critical step in today’s economy. The cost of building materials and labor has skyrocketed. If your homeowners’ policy limit was set five years ago, it might not be enough to rebuild your home at current market prices. Aligning your coverage with inflation is the ultimate “surprise-preventer.”

4. Check Your Liability Limits

As your career progresses and your net worth grows, your liability risk increases. If you are sued after an accident, are your current limits enough to protect your savings and home? A quick “checkup” on your liability levels ensures your hard-earned assets remain yours.

5. Review Your Discounts

Insurance companies frequently roll out new discounts for things like:

  • Installing a smart home security system.
  • Reaching a certain age or retirement status.
  • Bundling multiple types of insurance.
  • Going “paperless” with your billing.

Pro Tip: Small updates made during a routine review can often lower your premium, effectively paying you back for the 10 minutes you spent checking in!

Small Updates Today, Feeling Secure Tomorrow

Insurance shouldn’t be a mystery. It’s a tool designed to protect your future. By treating your policy review like a standard financial checkup, you move from being “reactive” to “proactive.”

Don’t wait for a claim to find out you’re under-covered. A 10-minute investment today prevents a lifetime of “what-ifs.”

June Blooms and Home Rooms: Updating Protection for Summer Renovations

June brings warmer weather, blooming gardens, and the start of home renovation season. Whether a project involves modernizing a kitchen with stone countertops, transforming a primary bathroom into a spa-like retreat, or adding an outdoor deck for summer entertaining, upgrading a living space is a major investment.

While choosing finishes and tracking construction timelines takes up most of the planning energy, updating the property insurance policy is a critical step. Failing to adjust coverage during or after a remodel can leave new investments vulnerable to major financial gaps.

Why Renovations Change Coverage Needs

A standard homeowners policy is built around the estimated cost to rebuild the home as it stands today. When structural changes occur or premium materials are introduced, that rebuilding cost shifts.

  • Increased Rebuilding Costs: Installing custom cabinets, professional-grade appliances, or premium flooring raises the physical value of the structure. If a fire or severe storm occurs and the policy limits reflect the pre-renovation home, the payout will fall short of the actual cost to replace those new materials.
  • Expanded Square Footage: Adding a room, finishing a basement, or building a covered patio expands the footprint of the home. This extra space must be factored into the dwelling coverage to maintain accurate protection.
  • Theft of Materials: Renovation sites often hold uninstalled materials like lighting fixtures, tools, or hardwood flooring planks. Standard policies frequently exclude items that are stolen before they are permanently attached to the structure, making a quick coverage check vital while work is underway.

Privately and Respectfully: Handling Sensitive Assets

Major home overhauls often prompt a deeper look into what is kept inside the house. When updating a policy to reflect structural changes, it is also an ideal time to review personal property limits—especially for highly personal, high-value assets like firearms.

Firearm ownership is deeply personal. Conversations regarding their protection should always be handled privately, respectfully, and clearly.

Standard homeowners insurance policies typically cap the payout for the theft of firearms at a low sub-limit, often between $1,500 and $2,500 for the entire collection. If you own multiple firearms or higher-value pieces, a basic policy will not cover a major loss.

Confidential Protection Options

Reviewing these limits does not mean broadcasting personal details. Protection can be enhanced discreetly using standard underwriting options:

  • Scheduled Personal Property: High-value pieces can be listed individually on a policy with an appraisal or sales receipt. This data remains strictly confidential within a secure file. Scheduled items generally receive broader protection, including coverage for accidental damage or loss outside the home, usually with no deductible.
  • Blanket Limit Increases: For those who prefer not to itemize specific pieces, raising the total blanket limit for the firearm category increases the maximum payout for the collection as a whole without requiring an itemized list.

Clear Next Steps for Your Project

As a June renovation gets underway, keeping a clear checklist prevents unexpected complications later.

Before construction begins, verify that the contractor carries active liability and workers’ compensation coverage. Keep receipts and take clear photos of the progress and final finishes. Once the dust settles, a straightforward review of the final numbers with a professional keeps the updated home, new investments, and personal collections accurately protected.

Auto Insurance & Road Trip Season

Road Trip Season Is Here

May often marks the beginning of road trip season. With warmer weather and long weekends ahead, more drivers are hitting the road for travel, events, and everyday activities.

Before heading out, it’s worth taking a closer look at your auto insurance. Long drives and unfamiliar routes can increase the chances of unexpected situations.

Start With Your Coverage

Start by reviewing your liability limits. These play a key role if you’re involved in an accident that impacts others. It’s also helpful to check if you have collision and comprehensive coverage in place.

Helpful Add-Ons for Travel

Additional features like roadside assistance and rental reimbursement can also come in handy during travel. A flat tire or breakdown is never convenient, but having support available can make the situation easier to manage.

Who’s Behind the Wheel

Another consideration is who will be driving. If multiple people are sharing driving responsibilities, it’s important to confirm they’re properly listed on your policy if needed.

Don’t Skip Maintenance

Vehicle maintenance also plays a role. Checking tires, brakes, and fluid levels before a long trip can help reduce the risk of issues along the way.

Be Ready Before You Go

Taking a few minutes to review your coverage before travel can help you stay focused on the road ahead. Because when plans are in motion, having the right protection in place helps keep everything moving forward.

May often marks the beginning of road trip season. With warmer weather and long weekends ahead, more drivers are hitting the road for travel, events, and everyday activities.

Before heading out, it’s worth taking a closer look at your auto insurance. Long drives and unfamiliar routes can increase the chances of unexpected situations.

Let’s Get You Road-Ready

Before your next trip, take a moment to review your auto coverage and make any updates needed for the road ahead. From liability limits to added protections like roadside assistance, a quick check-in can help you feel more prepared for whatever comes your way. Reach out to start the conversation and explore options that support your travel plans.

Navigation Update: The 2026 Milestone for Massachusetts Boaters

As of April 1, 2026, the Hanson-Milone Boater Safety Act marks a major turning point for recreational boating in the Commonwealth. While the law was passed in early 2025, this year represents the first hard deadline for a large segment of the boating community. For insurance agencies and vessel owners alike, this shift from “optional education” to “mandatory certification” changes the landscape of maritime risk management.

The 2026 Deadline: Who is Affected?

The new regulations require operators of all motorized vessels—including personal watercraft like Jet Skis—to carry a state-approved boating safety certificate. The 2026 update specifically targets a key demographic:

  • Birthdate Trigger: Anyone born after January 1, 1989, is now required to have completed an approved safety course by April 1, 2026.
  • Grace Period: While the law takes effect in April, the Massachusetts Environmental Police have indicated a ramp-up period, with active penalties and fines scheduled to begin on September 1, 2026.
  • The Next Wave: Operators born on or before January 1, 1989, are currently in a transition period and have until April 1, 2028, to comply.

Why Insurance Agencies are Prioritizing This Change

For local insurance agencies, the 2026 deadline is more than just a regulatory hurdle; it is a tool for promoting safer waterways. From a coverage perspective, a certified boater is statistically less likely to be involved in a major accident.

Here is how the 2026 requirements intersect with your insurance policy:

  • Verification of Competency: In the event of a liability claim, proving that the operator was in full compliance with state law—including holding the 2026 mandatory certificate—is a key factor in a smooth claims process.
  • Discount Eligibility: Many carriers provide “Safe Boater” discounts. With the 2026 mandate now in place, providing your agency with a copy of your new certificate is an easy way to verify your eligibility for lower premiums.
  • Policy Reviews: This regulatory shift provides a perfect opportunity to review vessel values and liability limits. As more people head to the classroom to get certified, agencies are seeing an uptick in owners who want to better understand their total risk profile.

Quick Guide to Compliance

RequirementDetail
Vessel TypeAll motorized boats and Personal Watercraft (PWC).
Course ContentNavigation rules, emergency response, and local laws.
CertificateMust be carried on the vessel (digital or physical).
PenaltyFines for non-compliance start after Sept 1, 2026.

Preparing for the Season

The goal of the Hanson-Milone Act is to standardize the knowledge of everyone on the water, reducing the “operator inexperience” factor that leads to many avoidable incidents. By securing your certification before the April deadline, you avoid the rush and the potential for late-season fines.

Whether you are navigating the coast or enjoying one of our many inland lakes, staying current with state requirements is a hallmark of a responsible owner. Let us know when you receive your new certificate and we will confirm that your coverage aligns with these updated standards.

Don’t Get Swamped: Who Really Needs Flood Insurance and Why It’s Non-Negotiable

Flooding is the most common and costly natural disaster in the United States, yet many homeowners still operate under the dangerous misconception that their standard homeowner’s policy provides adequate protection. As your local independent insurance agent, we’re here to clear up the confusion: Standard homeowners insurance policies do not cover flood damage. A separate flood insurance policy is essential for financial protection—and it might even be required for your property.

If you are buying or own a home, asking “Do I need flood insurance?” is one of the most important questions you can ask. The answer is almost always yes.

Who Needs Flood Insurance? The Definitive Answer

While the most obvious candidates are those in high-risk areas, the reality is that everyone has some level of flood risk. Flood insurance is not just for coastal homes or river towns; it’s a necessary form of property protection for virtually any location.

The Mandated Buyer: High-Risk Flood Zones

If your property is located in a Special Flood Hazard Area (SFHA), often designated as a high-risk Flood Zone on FEMA maps (e.g., Zones A or V), flood insurance is legally mandatory if you have a federally backed mortgage (which includes most mortgages).

  • Why it’s Required: Lenders require this coverage to protect their financial investment. Without it, a flood loss could result in a total default on the loan.

The Smart Investor: Moderate- to Low-Risk Areas

This is where the biggest misconception lies. Did you know that nearly 30% of all flood insurance claims come from properties outside of high-risk areas?

  • Flash Flooding is Universal: Heavy rain, poor drainage, rapid snowmelt, or even a levee breach can cause devastating flash floods anywhere—even far from a river or coast.
  • Low-Cost Options: Homeowners in moderate-to-low risk zones often qualify for a lower-cost Preferred Risk Policy (PRP) through the National Flood Insurance Program (NFIP), providing robust coverage at a highly affordable rate.

The Financially Prudent: All Homeowners and Renters

Whether you own a luxury home or rent an apartment, flooding can cause significant financial devastation.

  • Homeowners need coverage for the building structure (up to $250,000 via NFIP) and their personal contents.
  • Renters need a contents policy to protect their belongings (up to $100,000 via NFIP), as their landlord’s policy will only cover the building structure.

Why You Need Flood Insurance: Protection, Security, and Recovery

The cost of flood damage is staggering. Even just one inch of water can cause over $25,000 in damage to a home. Without a dedicated flood policy, those costs come straight out of your pocket.

Homeowners Insurance Doesn’t Cover Floods

This is the single most critical reason to buy a separate policy. Standard homeowners insurance covers damage from things like wind, fire, and burst pipes, but it explicitly excludes damage caused by external flooding or rising water.

Government Disaster Aid is Insufficient

Many people mistakenly believe federal disaster assistance (like FEMA grants or low-interest SBA loans) will cover their losses. The truth is:

  • Disaster Declarations are Rare: Federal aid is only available if the President issues an official disaster declaration, which happens in less than half of all flooding events.
  • Aid is Not Insurance: Even when declared, aid is usually in the form of low-interest loans you must repay or grants that barely cover the basics. Flood insurance is the fastest and most comprehensive path to financial recovery.

Protecting Your Most Valuable Asset

Your home is likely your biggest financial asset. Flood insurance provides the funds necessary to rebuild and repair the structure, foundations, utility systems (furnaces, water heaters), and finished surfaces like drywall and flooring.

Simplicity for Real Estate Transactions

Having a current flood policy makes your home a more attractive asset for buyers, especially those using a mortgage. When you sell, the lender will likely require the buyer to have a policy, and having one already in place simplifies the closing process. As an independent insurance agent, we can help you provide a policy that keeps your real estate investment protected and transferable.

Act Now: The Critical 30-Day Waiting Period

One final, crucial point: NFIP flood insurance policies typically have a 30-day waiting period before coverage goes into effect. You cannot wait until a hurricane is named or heavy rains are forecasted to purchase a policy. By the time a risk is imminent, it’s already too late.

Don’t delay protecting your home and your financial future. Contact us to assess your specific flood risk and secure the protection your property deserves.

Mid-Winter Home Maintenance Checklist to Prevent Claims

February is a tricky month for homeowners. Winter isn’t over, but temperatures often fluctuate enough to create new risks. A little proactive home maintenance now can help prevent costly insurance claims later.

Start with your gutters and downspouts. Ice buildup can cause blockages that force melting snow into unwanted areas, including under your roofline. Clearing debris reduces the risk of leaks and ice dams. While examining the roof, look for loose shingles or damage caused by earlier storms.

Inside the home, check for drafts around doors and windows. These small leaks not only increase heating bills but also raise the likelihood of frozen pipes. Pipes in unheated areas—such as garages, crawl spaces, and attics—should be insulated, and cabinet doors may need to stay slightly open during cold spells.

Next, test smoke and carbon monoxide detectors. Winter heating systems run constantly, increasing the risk of fire or carbon monoxide exposure. Replace batteries and confirm devices are functioning properly.

Basements also need attention. Moisture from melted snow can seep in through cracks or clogged exterior drains. Inspect sump pumps, foundation walls, and basement windows for early warning signs.

With a few preventive steps, homeowners can reduce the chance of winter-related damage and protect their property through the final stretch of the season.

Small Business Insurance: New Year, New Risks – Why Your Policy Needs a January Review

Why Small Business Owners Should Review Their Commercial Insurance Coverage

The start of a new calendar year is more than just a fresh page—it’s a critical moment for small business owners to assess and adjust their operations. Your small business insurance policy should be at the top of this review list. As your business evolves, so do the liabilities you face, and inadequate commercial insurance coverage can leave your company exposed to financial loss.

January: The Best Time for a Business Insurance Audit

Why kick off the year with an insurance review? Your business operations in the previous year often involve changes that directly impact your risk profile:

  • Growth and Expansion: Did you hire new employees, increase inventory, or lease a larger office space?
  • New Equipment/Assets: Purchasing new machinery, technology, or vehicles changes the value of your assets that need protection.
  • Updated Services or Products: Launching a new offering may introduce professional or general liability risks not covered by your current policy.
  • Changing Regulations: New state or industry-specific compliance requirements might necessitate different forms of business liability insurance.

Key Areas to Update in Your Small Business Insurance Policy

A thorough January review helps identify gaps in your protection. Focus on these critical types of small business insurance:

1. General Liability Insurance (GLI)

Did your client interactions or on-site foot traffic increase last year? General liability insurance protects against claims of bodily injury or property damage for which your business could be held responsible. Verify that your current liability limits align with your updated exposure, especially if you moved to a new location or handle more high-value projects.

2. Commercial Property Insurance

This coverage protects the physical assets of your company—buildings, equipment, inventory, and supplies. Review the following:

  • Inventory Value: If sales surged, your current coverage limits might undervalue your stock, leaving you under-indemnified after a loss event.
  • New Asset Valuation: Have you purchased new computers, manufacturing equipment, or furniture? Update your asset schedule to reflect the current replacement cost.
  • Business Interruption Coverage: Has your revenue increased? This vital component, often bundled with property insurance, must reflect your current profitability to adequately cover lost income following a covered peril.

3. Workers’ Compensation Insurance

If your employee count changed, or if roles shifted to include higher-risk duties, your Workers’ Comp insurance classifications and premium will need an adjustment. Failing to accurately report payroll and job functions can lead to penalties or claims issues down the line.

4. Professional Liability (E&O) and Cyber Insurance

For service-based businesses (consultants, IT, marketing agencies), Professional Liability Insurance (Errors & Omissions) is crucial. If you begin offering new, higher-risk services (e.g., handling client data, providing complex advice), re-evaluate your limits.

Furthermore, with cyber threats rising, all small business owners should review their Cyber Liability Insurance to confirm it covers data breaches, regulatory fines, and business interruption from a cyber-attack.

Your Action Plan for a January Insurance Review

Don’t wait until a claim occurs to discover a coverage shortfall. Follow these steps to optimize your commercial insurance in the new year:

  1. Document All Changes: Create a detailed list of new hires, large asset purchases, revenue changes, and any new services/products from the past 12 months.
  2. Contact Your Broker: Schedule a dedicated review with your small business insurance agent or broker to discuss the documented changes.
  3. Compare Quotes: The market is always changing. Use the new year as a trigger to quickly compare business insurance quotes to confirm you are getting competitive rates for the required coverage.
  4. Confirm Deductibles: Verify that your current deductibles are financially manageable for your business.

Protecting your assets with the right coverage is a foundational element of a strong business plan. Start the year right by securing comprehensive small business protection.

Gear Up for Winter: Auto Insurance Tips for Snow and Ice

Winter brings a unique set of challenges for drivers, from icy roads to snowdrifts. While preparing your vehicle for the cold weather is crucial for safety, understanding how your auto insurance protects you during these treacherous months is equally important. Taking proactive steps now can save you from a headache and a financial hit when the temperatures drop.

🚗 Preparing Your Vehicle for Winter Roads

Before the first snowflake falls, dedicate some time to winterize your car to prevent breakdowns and make driving safer. Tires are your vehicle’s most vital connection to the road. You should inspect the tread depth to ensure you have enough grip for slippery surfaces. You can use the classic “penny test”—if you can see the top of Lincoln’s head when you insert a penny head-first into a tread groove, you should probably consider new tires. Also, remember that cold weather causes air pressure to drop, so check your tires regularly to improve handling and fuel efficiency.

Beyond the tires, focus on your vehicle’s essential fluids and systems. Battery health is critical; cold temperatures significantly reduce battery power, making it essential to have it tested, especially if it’s older than three years. In terms of fluids, check your antifreeze mixture to prevent your engine from freezing, and top off your windshield washer fluid with a winter-grade solution that resists freezing. Finally, ensure your brakes are in top condition and that all of your exterior lights are functional so you can clearly see and be seen on dark, snowy days.

🧰 Don’t Drive Without a Winter Emergency Kit

Even the best-prepared car can be unpredictable in a snowstorm. Having a well-stocked emergency kit in your trunk is crucial if you get stranded or need quick assistance. This kit should contain several essential items designed to keep you warm, safe, and visible.

Your must-have emergency list includes:

  • Traction and Tools: Jumper cables, a small shovel, and a bag of sand, cat litter, or rock salt to help your tires gain traction if you get stuck.
  • Warmth and Safety: Warm blankets, hats, and gloves to retain heat, a flashlight with extra batteries, and a basic first-aid kit.
  • Communication: A fully charged cell phone and a portable charger are vital for calling for help.
  • Sustenance: Non-perishable food and water, in case you are delayed for a significant amount of time.

🛡️ What Your Auto Insurance Covers in Winter

Understanding your policy is key to peace of mind during the challenging winter months. Your auto insurance is designed to protect you from common winter accidents and damage, but only if you have the right coverage.

  • Collision Coverage is what pays for damage to your vehicle if you are involved in an accident with another car or an object. If you slide on black ice and hit a guardrail, a light pole, or end up in a ditch, your collision coverage helps pay for your car’s repairs, minus your deductible. Since loss of control is so common in winter, this is one of the most critical coverages to maintain.
  • Comprehensive Coverage handles damage to your vehicle resulting from “non-collision” events. This is especially relevant in winter for events like hail or wind damage from a bad storm, or if a tree branch falls on your car due to heavy ice or snow. It also covers damage from theft, vandalism, and accidents with animals, which can still occur during the colder months.
  • Liability Coverage is mandatory in almost every state and is there to protect you financially if you are at fault for an accident. If you slide on an icy overpass and cause an accident that injures another person (Bodily Injury) or damages another vehicle or someone’s property (Property Damage), your liability coverage will step in to cover those costs, up to your policy limits. Remember, this coverage never pays for damage to your own vehicle.

As the snow falls and the temperatures drop, the combination of a well-prepared vehicle, a stocked emergency kit, and the right auto insurance coverage is your best defense against winter’s driving hazards. Take a moment to check your tires, test your battery, pack those blankets, and, most importantly, review your policy’s Collision and Comprehensive coverage with us. Don’t let a slick road result in a financial headache. Being proactive now prepares you for the challenges of snow and ice with confidence and security, knowing you’re protected on all fronts.